As we head into the final months of the year, now is a good time to review potential tax planning opportunities before December 31. While many traditional year-end strategies remain available, the One Big Beautiful Bill Act (“OBBBA”) introduced several tax law changes that may affect your planning decisions. Taking a fresh look at your tax situation before year-end can help you identify opportunities to reduce taxes and make the most of the new tax rules.
Maximizing Tax-Advantaged Contributions
Contribute to your IRA and employer-sponsored or self-employed Retirement Plan accounts up to the allowed limits. See the chart below for the maximum amount you can contribute to your plan.
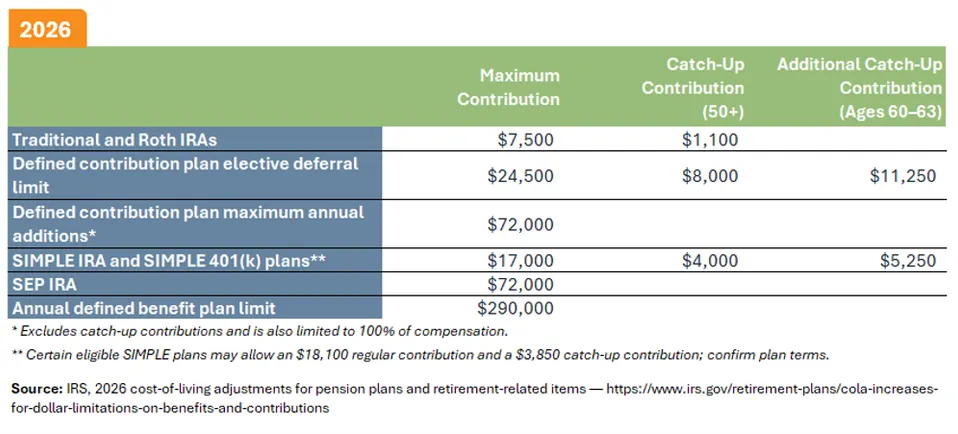
Beginning this year, if you are employed and your FICA wages from the employer sponsoring your retirement plan exceed the applicable threshold in the prior year, your catch-up contribution must be directed into the Roth portion of your retirement plan. However, not all employers offer this option, so check with your retirement plan administrator. For 2026 catch-up contributions, the threshold is $150,000 based on 2025 FICA wages. Furthermore, if your employer-sponsored plan allows voluntary after-tax contributions and either in-plan Roth conversions or in-service rollovers, total annual additions may generally reach $72,000 in 2026, excluding permitted catch-up contributions. The amount available for after-tax contributions is reduced by regular employee deferrals and employer contributions or other allocations. These after-tax contributions can be used as part of a “mega-backdoor Roth” strategy, meaning these contributions can be converted within the plan or rolled into a Roth IRA, where they can grow tax-free. Qualified withdrawals can be made tax-free in the future.
If you are enrolled in a high-deductible health plan (HDHP) and have a Health Savings Account (“HSA”), consider maximizing your contributions. The maximum contributions allowed for 2026 are $4,400 for individuals and $8,750 for families, with an additional $1,000 catch-up contribution for those age 55 and older. You generally have until April 15, 2027 to make HSA contributions for the 2026 tax year. Additionally, make sure to retain records of qualified medical expenses for any current or future HSA reimbursements. If you have already met your health insurance deductible for the year, consider completing any additional medical procedures before year-end. If you are not eligible to contribute to an HSA, your employer may offer a general-purpose healthcare Flexible Spending Account (“FSA”), which allows you to set aside up to $3,400 pre-tax in 2026 for eligible medical expenses.
If you contribute to an HSA, you generally cannot also participate in a general-purpose healthcare FSA. However, you may still qualify for a Limited Purposes FSA for eligible dental and vision expenses, as well as a dependent care FSA if you have a child under age 13 or another qualifying dependent who cannot care for themselves. For 2026, a dependent care FSA allows you to set aside up to $7,500 pre-tax, or $3,750 if married filing separately, to help cover eligible childcare and dependent care expenses. Because unused funds in an FSA and/or LPFSA above the IRS carryover limit ($680 in 2026) are generally forfeited, confirm your plan’s eligible-expense and claim-submission deadlines with your HR department before making an election.
Maximizing contributions to your IRA, workplace or self-employed retirement plan, and an HSA or FSA remains one of the simplest and most effective ways to reduce taxable income now or provide tax-free income in the future. In addition to the potential tax savings, these accounts can help build retirement assets and set aside funds for future healthcare expenses. Keep in mind that Roth and non-deductible contributions do not reduce taxable income in the years the contributions are made.
Strategies to Help Minimize Tax Burden
Harvest Losses from Taxable Accounts Selling securities for a loss, referred to as tax-loss harvesting, may help reduce your tax bill now and in the future. Even if you held the securities for less than one year, losses from the sale may offset short-term and long-term capital gains realized in 2026. Keep in mind that capital losses are netted against all capital gains, including those from the sale of a business or real estate. Any remaining net losses can offset up to $3,000 of ordinary income, or $1,500 if married filing separately, and unused losses can be carried forward to help reduce future tax bills. Note that you generally cannot deduct a loss on a security if you purchase the same or a substantially identical security within 30 days before or after the sale, as this is considered a wash sale. If you had significant losses in 2025 or an earlier year, you may have capital-loss carryforwards that can be applied to your 2026 taxes. Your advisor may be working to identify and, where appropriate, realize available capital losses within your managed taxable accounts prior to year-end.
Charitable Giving & New Rules starting in 2026 Charitable donations remain a valuable tax planning tool, allowing taxpayers to support charitable organizations while potentially offsetting a portion of their tax liability.
There are three major changes affecting charitable giving beginning in 2026, as introduced by the OBBBA. (1) If you are itemizing deductions, you generally may only deduct charitable contributions exceeding 0.5% of your adjusted gross income (“AGI”). (2) If you are taking the standard deduction, you are now able to deduct up to $1,000 of qualifying cash contributions, or $2,000 if filing jointly. (3) There is a new limitation in place for taxpayers who are itemizing and are in the highest 37% tax bracket. The limitation effectively caps federal tax savings from itemized deductions at 35 cents per deductible dollar.
These changes create several charitable giving planning opportunities. One strategy to consider is “bunching” multiple years of charitable contributions into a single tax year and contributing those funds to a donor-advised fund (DAF). This approach may allow a taxpayer to exceed the new AGI threshold, making charitable deductions more valuable while continuing to support long-term philanthropic goals. Other strategic giving, such as donating appreciated assets or using a qualified charitable distribution (QCD) to satisfy all or part of your RMD, can further reduce taxable income and ultimately lower the overall tax liability. For more information, read our piece on Thoughtful Charitable Giving to help make your charitable giving the most impactful.
Reinvesting the taxable gain into Qualified Opportunity Zone (“QOZ”) Beginning January 1, 2027, the updated Qualified Opportunity Zone (QOZ) 2.0 program will take effect, offering many of the same tax benefits as the original program. In general, eligible capital gains must be invested in a QOZ Fund within 180 days of the gain event. As a result, gains recognized later this year may still qualify for the new program if the 180-day investment window extends into 2027.
Under QOZ 2.0, the original gain can generally be deferred for up to five years unless the investment is sold, exchanged, or another recognition event occurs sooner. Investors who hold their investment for at least five years may qualify to exclude 10% of the deferred gain from taxation, with the exclusion increasing to 30% for investments made in qualified rural opportunity funds. In addition, if the investment is held for at least 10 years, any appreciation attributable to the QOZ investment may be excluded from federal income tax, provided all program requirements are met. This benefit generally applies to appreciation realized over a period of up to 30 years.
Making the Most of a Lower Income or Tax Bracket Year
This year, you may be eligible for several tax provisions introduced under the OBBBA, such as the enhanced senior deduction, increased state and local tax (SALT) deduction limits, deduction for qualified auto loan interest, and new deductions for eligible overtime pay and tip income. These provisions may have reduced your taxable income and placed you in a lower marginal tax bracket. If so, this may present valuable tax planning opportunities. By being proactive, you can use strategies such as Roth conversions, capital gain harvesting, and other income-recognition techniques that may help reduce your lifetime tax liability.
Convert your Traditional IRA to a Roth IRA If you anticipate a future increase in income that may put you in a higher income tax bracket, consider converting a portion of your traditional IRA or other qualified accounts to a Roth IRA. A Roth IRA can be advantageous as qualified withdrawals are tax-free, unlike distributions from a traditional IRA. A conversion can be used to reduce the tax impact future required minimum distributions (“RMDs”) may have on your taxable income. Market downturns often create opportunities to convert from a traditional IRA to a Roth IRA at a lower taxable value, with the potential to recover tax-free growth. Keep in mind that the amount converted is taxable in the year of the conversion and, once placed in a Roth IRA, it cannot be reversed. Therefore, consult with your tax professional before deciding to convert.
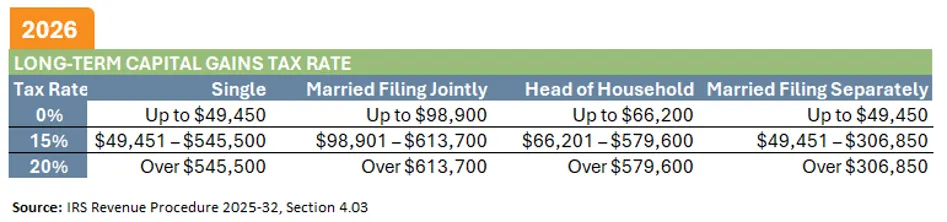
Harvest Gains from Your Taxable Accounts If you find yourself in a low tax bracket for 2026, you may wish to take advantage of lower tax rates on capital-gain income. It may benefit you to realize gains from a concentrated stock position to further diversify your asset allocation and increase the cost basis of your portfolio. This strategy may also benefit pass-through business owners who expect a net operating loss from their business in 2026.
Planning Beyond Today
Make Annual Exclusion Gifts to Family For those looking to help family members, consider making annual tax-free gifts to loved ones. In 2026, the annual gift tax exclusion allows you to transfer up to $19,000 per recipient in cash or property without reducing your lifetime gift and estate tax exemption. Married couples can give a combined $38,000 to each child, grandchild, or other individual using their annual exclusions. These gifts generally do not require a gift tax return unless you elect to split gifts with your spouse or another reporting requirement applies. Gifting shares of stock or other investments can help foster an interest in investing while reducing the temptation to spend the gift immediately. If gifting cash by check, make sure the check is deposited before year-end for the gift to count toward your 2026 annual exclusion.
Consider creative ways to support your children and grandchildren, such as helping fund their education through a 529 college savings plan or jump-starting their retirement or long-term savings through a Trump Account.
With a 529 college savings plan, a special five-year election allows you to front-load up to five years’ worth of annual exclusion gifts into a 529 plan at once, which is up to $95,000 per individual or $190,000 for a married couple this year. Beginning in 2026, up to $20,000 per beneficiary may be withdrawn annually from 529 plans for qualified K–12 education expenses. Qualified expenses have also expanded beyond tuition to include items such as curriculum materials, books, tutoring, certain testing and dual-enrollment fees, qualifying educational therapies and certain post-secondary credentialing expenses. If there are unused funds in a 529 plan, you may be able to roll them into a Roth IRA for the beneficiary. These rollovers are subject to annual Roth IRA contribution limits, a $35,000 lifetime limit, and other requirements, including that the 529 account generally must have been open for at least 15 years.
You may also consider contributing to a Trump Account for an eligible child. These accounts are intended to encourage long-term saving and can be funded by parents, grandparents, and other family members. For those looking for an alternative to direct cash gifts, a Trump Account may provide a tax-advantaged way to help a child build savings for future education, a first home, or other financial needs. Before contributing, be sure to reach out to understand the applicable contribution limits, eligibility requirements, and distribution rules. As with any gifting strategy, consult your advisor and tax professional to determine which approach best aligns with your family’s goals and circumstances.
Read our piece on Financially Savvy Gift Ideas for other creative gifting ideas.
Just a Reminder
Take Required Minimum Distributions (“RMDs”) from Retirement Plans If you haven’t done so already, make sure to take your RMDs from your IRA(s) or qualified retirement plan(s) before December 31, 2026. The IRS mandates that a minimum amount must be distributed from certain retirement accounts each year. The RMD age changed with the SECURE 2.0 Act, moving from age 72 to age 73, and is set to increase again in 2033 to age 75. If you fail to distribute the required amount, you may face a penalty of 25%, or 10% if corrected timely, on the amount that should have been withdrawn but wasn’t. Remember, RMDs are not required from Roth IRAs or designated Roth accounts during the account owner’s lifetime.
If you were born in 1953, you will turn 73 this year and generally will need to take your first RMD. The latest you can delay this first RMD is April 1, 2027, but be aware that you will then need to take two RMDs in 2027. This approach may be beneficial if you anticipate having higher income in 2026 and expect lower income in 2027. We recommend considering income tax withholding from your IRA distributions to help with cash-flow planning.
RMDs may also apply to certain inherited retirement accounts. The primary factors that determine whether an RMD must be taken from an inherited retirement account, as well as the timing and requirements, are as follows: (1) the date the account holder passed away, (2) the beneficiary’s relationship to the deceased account owner and (3) the type of retirement account inherited. For more information, read our pieces on FAQs About RMDs or So You’ve Inherited an IRA.
Pay Taxes on Deferred Capital Gains Reinvested in QOZ 1.0 If you deferred capital gains by investing in a Qualified Opportunity Zone (QOZ) fund under the original QOZ program (QOZ 1.0), know that the deferral period ends this year. As a result, the deferred capital gain will become taxable and any tax due will generally need to be paid by April 15 of next year. As part of your year-end planning, confirm that the deferred gain has been properly reported and factored into your tax projections. You should also evaluate whether you have sufficient liquidity to cover the resulting tax liability and whether a Q4 estimated tax payment is warranted to avoid potential underpayment penalties. Consult your tax advisor to determine whether an additional estimated payment is required based on your specific circumstances. Importantly, the deferred capital gain becoming taxable does not require you to sell your QOZ investment. Investors who continue to hold their QOZ fund and satisfy the applicable holding period requirements may still qualify for favorable tax treatment on future appreciation of the investment.
Many tax-saving opportunities are time-sensitive, so it’s worth reviewing your options before year-end. Thoughtful planning today can help reduce taxes and better position yourself for the future.
If you could benefit from a conversation with our advisory team, we would be happy to provide a complimentary consultation.
Important Disclosure: This report is for informational purposes only. Opinions expressed herein are subject to change without notice. Beacon Pointe has exercised all reasonable professional care in preparing this information. The information has been obtained from sources we believe to be reliable; however, Beacon Pointe has not independently verified, or attested to, the accuracy or authenticity of the information. Nothing contained herein should be construed or relied upon as investment, legal, or tax advice. Forward-looking statements are based on current legislation. Future changes may impact the applicability of these provisions. Tax benefits are contingent upon satisfying applicable statutory and regulatory requirements and may be affected by future changes in tax laws. All investments involve risks, including the loss of principal. Alternative investments involve specific risks that may be greater than those associated with traditional investments, including illiquidity, limited transparency, valuation uncertainty, and the potential loss of principal. Certain alternative investments may be offered only to clients who meet specific suitability requirements, including minimum net worth tests. There is no assurance that any investment will meet its investment objectives or that substantial losses will be avoided. Past performance is no guarantee of future results.
Copyright © 2026 Beacon Pointe Advisors, LLC®. No part of this document may be reproduced