Charitable giving not only improves the lives of others but has been shown to increase happiness more than personal spending on oneself.1 We have summarized the key factors to help make your charitable giving the most impactful.
Choosing a Charity
We recommend finding a charity that aligns with your values. Begin by searching for charities that help causes that are important to you. Searching on websites like candid.org, givewell.org, and greatnonprofits.org can provide details about how the charity uses the donations. After finding a few charities that inspire you, we recommend scheduling on-site visits to your top charities and interviewing managers involved with the charity before making any significant gift. If time allows, volunteering is a great way to get to know the charity, and to see firsthand how they run their business and whether they accomplish their stated goals. You might ask your children and grandchildren to volunteer with you for a few hours to share the benefits of giving back and create lasting family memories. Community foundations are another good way to connect to local charities, as the staff can provide further details of charities working for causes you may want to support.
Maximizing the Tax Benefits from Giving
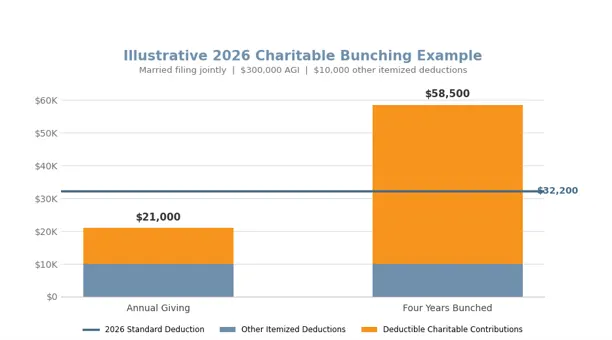
The One Big Beautiful Bill Act, signed July 4, 2025, changed the federal rules for charitable deductions beginning in 2026. Taxpayers who do not itemize may now deduct up to $1,000 ($2,000 for married couples filing jointly) of cash gifts made directly to eligible qualified charities. Gifts to donor-advised funds, supporting organizations, and private nonoperating foundations do not qualify. This deduction is available in addition to the standard deduction but does not reduce adjusted gross income (“AGI”). The 2026 standard deduction is $16,100 for single filers, $32,200 for married couples filing jointly, and $24,150 for heads of household. For taxpayers who itemize, a new 0.5% of AGI floor now applies to charitable contribution deductions. As a result, charitable contributions are deductible only to the extent they exceed 0.5% of AGI. A taxpayer with $300,000 of AGI, for example, receives no deduction for the first $1,500 of charitable gifts. In addition, taxpayers in the 37% federal income tax bracket may see the tax benefit of itemized deductions effectively limited to 35%, reducing the value of charitable deductions at the highest income levels. These changes increase the importance of strategic charitable planning. One potential strategy is bunching several years of gifts into one year, allowing a taxpayer to exceed both the standard deduction and the new AGI floor.
Types of Assets to Give
Taxpayers who itemize may be able to deduct gifts of cash, appreciated securities, real estate, personal property, vehicles, and life insurance. The value of donated time or services is not deductible, although certain unreimbursed expenses directly connected with volunteer work may qualify.
Cash gifts to qualified public charities are generally deductible up to 60% of AGI. Noncash contributions, such as donations of inventory, short-term capital gain property, and other ordinary income property, are generally limited to the donor’s adjusted basis, with a deduction limit that depends on the property and the receiving organization. Clothing and household goods generally must be in good used condition or better. Keep a bank record or written receipt for cash gifts. Contributions of $250 or more require a contemporaneous written acknowledgment, and noncash gifts over $500 generally require Form 8283. A qualified appraisal is generally required for noncash gifts over $5,000, subject to specific exceptions.
Long-term capital gain assets, such as appreciated publicly traded stock or real estate held for more than one year, can be highly tax-efficient assets to donate. A gift to a qualified public charity generally produces a deduction equal to fair market value, subject to a 30% of AGI limit; at the same time, the donor avoids recognizing the embedded capital gain on the contribution. A donor may elect to use a 50% of AGI limit, but the deduction is then reduced to the asset’s adjusted basis. Contributions exceeding the applicable AGI limit may generally be carried forward for up to five years.
Owners considering a gift of a closely held business interest should begin planning well before a sale becomes binding or practically certain. The charity must receive the interest and retain control over whether and when to sell it. If the sale is already binding or practically certain when the gift is made, the IRS may require the donor to recognize and pay tax on the gain. Closely held interests also require careful planning around valuation, qualified appraisal requirements, transfer restrictions, and the transaction itself. The donor should coordinate the gift with tax and legal counsel and the receiving charity before negotiations are far advanced.
Gifts to private nonoperating foundations and certain other organizations are subject to lower limits. Cash gifts are generally limited to 30% of AGI, and gifts of long-term capital gain property are generally limited to 20% of AGI. For most appreciated property contributed to a private nonoperating foundation, the deduction is reduced by the long-term capital gain that would have been recognized, which generally leaves a basis-level deduction. Qualified appreciated stock is an important exception and may qualify for a fair market value deduction. Confirm the organization’s deductibility status using the IRS Tax Exempt Organization Search tool.
Life insurance may be an attractive charitable giving option when a policy is no longer needed. To qualify for a current charitable deduction, the donor must irrevocably transfer all ownership rights to the charity. The deduction is generally limited to the lesser of the policy’s fair market value or the donor’s adjusted basis and is generally subject to the 50% of AGI limit for gifts to a public charity. Additional cash gifts used to pay future premiums may also be deductible under the rules for cash contributions. Before transferring a policy, confirm that the charity will accept it and coordinate the transfer with the charity, insurance carrier, CPA, and legal counsel. Policy loans, ongoing premium requirements, state insurable-interest rules, and the charity’s intended use of the policy can affect the result.
Alternate Ways of Giving
The simplest way to give to charity is by giving directly to the charity. However, putting thought into how you give can create flexibility and possibly increase your tax benefits. For a charitable gift with lasting impact, consider using a donor-advised fund (“DAF”). A contribution to a DAF is irrevocable and may qualify for a charitable deduction in the year it is made. The organization that administers the DAF, such as DAFgiving360, Fidelity Charitable, or a community foundation, legally owns and controls the contributed assets, while you retain the ability to recommend how the assets are invested and which eligible charities receive grants over time. This flexibility allows you to set up recurring grants, make gifts once a year, or involve children and grandchildren by letting them participate in grant recommendations. A DAF can also make it easier to bunch several years of charitable giving into one tax year while allowing grants to charities to be spread out over time.
Contributions can generally be invested, so even a little can go a long way, and many DAFs are inexpensive to establish with no minimum initial contribution. Remember, just like any charitable donation, there can be no quid pro quo: DAF assets cannot be used to purchase event tickets, memberships, or other personal benefits. A DAF grant may generally support a charitable pledge if the DAF provider makes no reference to the pledge and the donor receives no other benefit, although policies vary by provider. A DAF also cannot receive a qualified charitable distribution from an IRA.
Another alternative is a qualified charitable distribution (“QCD”), which allows an IRA owner age 70½ or older to transfer up to $111,000 in 2026 directly from an IRA to an eligible charity. The distribution is excluded from taxable income, is not also claimed as a charitable deduction, and can count toward the year’s required minimum distribution, potentially reducing AGI, Medicare income-related premiums, and other taxes. To maximize this benefit, the QCD should generally be completed before taking other IRA withdrawals because the first dollars distributed are treated as satisfying the required minimum distribution (RMD). Donor-advised funds, supporting organizations, and private foundations are generally not eligible recipients. The IRA custodian must send the funds directly to the charity, and the donor should obtain a written acknowledgment. Deductible IRA contributions made after age 70½ may also reduce the portion of future QCDs that can be excluded from income.
A related planning opportunity is the separate one-time election that allows an individual to transfer up to $55,000 in 2026 from an IRA to a charitable gift annuity, charitable remainder annuity trust, or charitable remainder unitrust funded only with QCDs. This amount counts toward the $111,000 annual QCD limit. Only the IRA owner, the owner’s spouse, or both may receive the income payments, and the income interest cannot be assigned. Payments are treated as ordinary income. A charitable gift annuity funded under this rule must begin fixed payments of at least 5% within one year. Because the election is available only once and has specific technical requirements, it should be coordinated carefully with the charity and the donor’s tax and legal professionals.
Charitable trusts can support larger or more complex gifts but are typically more expensive to establish and maintain. A charitable remainder trust provides payments to one or more noncharitable beneficiaries for life or a term of up to 20 years, with the remaining assets passing to charity. A CRT may sell appreciated property without immediate capital gain at the trust level, but the gain is tracked and generally passed through to beneficiaries as payments are made. To the extent payments are treated as long-term capital gain, they are generally taxed at lower federal rates than ordinary income. The strategy can therefore defer and spread the tax rather than eliminate it. A charitable lead trust makes payments to charity for a stated term, after which the remaining assets generally pass to family members or other beneficiaries. Depending on how the trust is structured, the donor may or may not receive an income tax charitable deduction. The income tax and transfer tax results vary significantly by structure, so these trusts require coordinated tax, legal, investment, and charitable planning.
Everyone Can Give
Even if you don’t have highly appreciated stock or much cash to give, making simple gifts of time, old clothes, or weekly donations to your church, place of worship, or local community charity will still go a long way. We encourage you to enjoy the gift of giving by incorporating philanthropy into your life.
If you could benefit from a conversation with our advisory team, we would be happy to provide a complimentary consultation.
1 Walsh, C. (April 2008). Money Spent on Others Can Buy Happiness. The Harvard Gazette.
*2026 federal tax figures reflect P.L. 119-21, IRS Revenue Procedure 2025-32, IRS Publication 505 (2026), and IRS Notice 2025-67. The chart is illustrative; actual deductions depend on the taxpayer’s circumstances, and the standard deduction is indexed annually.
*Sources include P.L. 119-21; Internal Revenue Service Publication 526, Charitable Contributions (2025); Publication 590-B, Distributions from Individual Retirement Arrangements (IRAs) (2025); Topic No. 506, Charitable Contributions; Revenue Procedure 2025-32; Notice 2017-73; IRS Publication 505 (2026); and Notice 2025-67.
Important Disclosure: This material is intended for general informational purposes only. Beacon Pointe Advisors does not offer legal or tax advice. Tax laws, regulations, and interpretations are subject to change. This material reflects federal tax law as of the publication date and does not address all federal, state, or local tax considerations. Please consult with the appropriate tax or legal professional regarding your circumstances. This information is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice. Only a tax or legal professional may recommend the application of this general information to any particular situation or prepare an instrument chosen to implement any design discussed herein. Nothing herein should be relied upon as personalized investment advice, nor should it be considered an individualized recommendation, offer or solicitation for the purchase or sale of any security or to adopt a specific investment strategy. An investor should consult with their financial professional before making any investment decisions. Beacon Pointe provides links for your convenience to other providers’ websites. Beacon Pointe is not responsible for errors or omissions in the material on third-party websites and does not necessarily approve or endorse the information provided.