The Quick Facts
- The third quarter demonstrated both the benefits and limitations of diversification in a rising-rate environment. The reset in yields has improved bonds’ income and return potential, reinforcing the value of diversification and disciplined rebalancing.
- Growth portfolios (70% Global Equity / 30% U.S. Aggregate bond) declined 1.6% in September, gained 0.1% during the third quarter, and are now up 8.2% year-to-date and 11.2% over the past twelve months.
- U.S. equities were mixed. The S&P 500 declined 0.3%, the Nasdaq 100 gained 3.3%, and the Russell 2000 fell 5.3% in September, as higher borrowing costs pressured smaller companies.
- The Federal Reserve raised interest rates for the first time since July 2023, increasing the federal funds rate by 0.25% to a range of 3.75% to 4.00%.
- U.S. government bonds experienced their worst month in four years. The 10-year Treasury yield rose 53 basis points in September and 81 basis points during the quarter to 5.28%, its largest quarterly move since 1994.
- Fixed-income losses were broad. The U.S. Aggregate Bond Index declined 2.6% in September, while investment-grade corporate and municipal bonds fell 2.7% and 4.4%, respectively. Higher yields now provide a more attractive starting point for income and future returns.
September Asset Class Performance
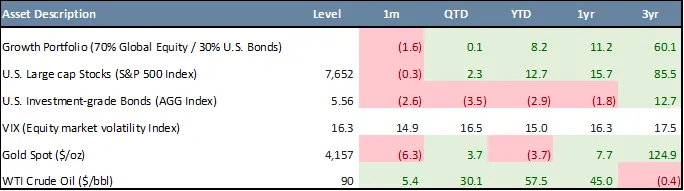
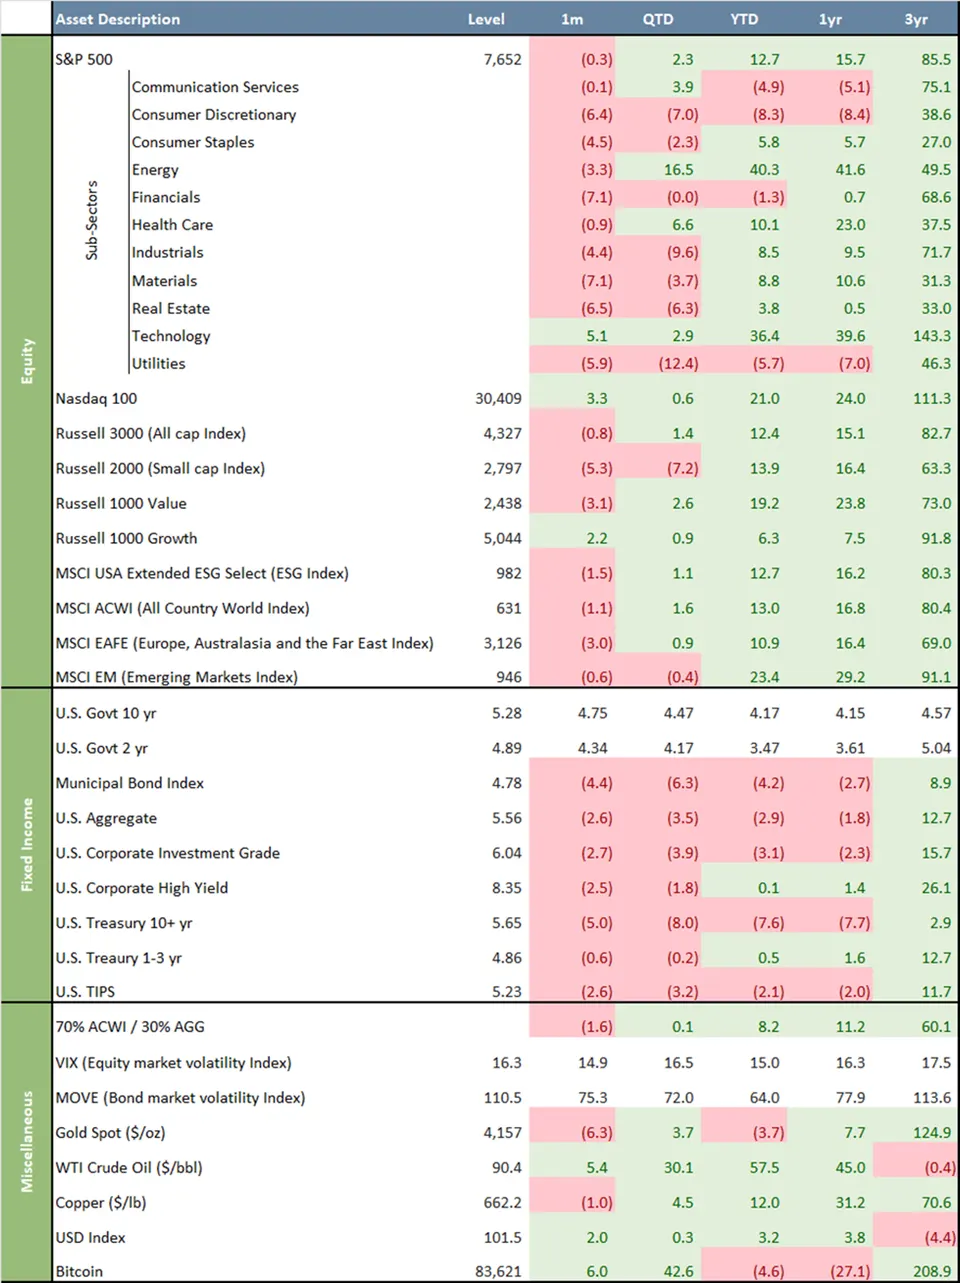
Markets ended the third quarter on an uneven note as rising interest rates and commodity prices weighed on most asset classes. U.S. large-cap equities remained resilient, while small-cap stocks, international equities, and fixed income declined during September. A traditional 70% Global Equity / 30% U.S. Aggregate bond growth portfolio declined 1.6% during the month, gained 0.1% during the quarter, and is now up 8.2% year-to-date and 11.2% over the past twelve months. Diversification provided less protection during the quarter as higher rates pressured several asset classes simultaneously.
U.S. equities were mixed. The S&P 500 declined 0.3% in September but gained 2.3% during the quarter and is now up 12.7% year-to-date. The Nasdaq 100 gained 3.3% during the month and 0.6% during the quarter, bringing its year-to-date return to 21.0%. Small-cap stocks came under greater pressure, with the Russell 2000 declining 5.3% in September and 7.2% during the quarter, although it remains up 13.9% for the year.
The divergence between growth and value continued. The Russell 1000 Growth Index gained 2.2% in September and 0.9% during the quarter, while the Russell 1000 Value Index declined 3.1% during the month but gained 2.6% during the quarter. Value remains well ahead year-to-date, returning 19.2% compared with 6.3% for growth. Maintaining exposure to both styles remains more sensible than attempting to predict which one will lead next.
Sector performance was highly dispersed. Technology gained 5.1% in September and 2.9% during the quarter, bringing its year-to-date return to 36.4%. Energy declined 3.3% during the month but gained 16.5% during the quarter and remains the strongest sector year-to-date, returning 40.3%. Healthcare and Communication Services gained 6.6% and 3.9% during the quarter. Rate-sensitive and economically cyclical sectors experienced greater pressure, with Utilities declining 12.4%, Industrials falling 9.6%, Consumer Discretionary losing 7.0%, and Real Estate declining 6.3%.
Global equities weakened in September. The MSCI All Country World Index declined 1.1% during the month but gained 1.6% during the quarter and is up 13.0% year-to-date. The MSCI Europe, Australasia and Far East Index fell 3.0% in September, reducing its quarterly gain to 0.9% and its year-to-date return to 10.9%. Emerging markets declined 0.6% during the month and 0.4% during the quarter but remain one of the strongest major equity markets in 2026, gaining 23.4% year-to-date. International exposure continues to provide access to different economic cycles, valuations, currencies, and sources of return.
The Federal Reserve delivered its first rate increase since July 2023 at its September meeting, raising the federal funds rate by 0.25% to a range of 3.75% to 4.00%. The move marked an important change in monetary policy and reinforced the Federal Reserve’s concern that inflation remains too high. The result was a sharp bond-market selloff. U.S. government bonds experienced their worst month in four years as investors repriced the outlook for inflation, monetary policy, and longer-term borrowing costs. The 10-year Treasury yield increased 53 basis points during September to 5.28% and rose 81 basis points during the quarter, its largest quarterly increase since the first quarter of 1994. The 2-year Treasury yield increased 55 basis points during the month to 4.89% and rose 72 basis points during the quarter. Losses were particularly severe among longer-duration securities.
Bond-market volatility also increased sharply. The MOVE Index rose from 75.3 at the end of August to 110.5 at quarter-end, while the VIX ended September at a relatively contained 16.3. The quarter’s primary source of market stress was not corporate earnings or equity volatility, but the repricing of inflation, Federal Reserve policy, and longer-term interest rates.
The Bloomberg U.S. Aggregate Bond Index declined 2.6% in September and 3.5% during the quarter, bringing its year-to-date return to negative 2.9%. Investment-grade corporate bonds declined 2.7% during the month and 3.9% during the quarter, while municipal bonds fell 4.4% and 6.3%, respectively. Although these losses were painful, higher yields improve the starting point for future bond returns. Bonds continue to play an important role in income generation, liquidity management, capital preservation, and diversification.
Commodities delivered mixed results. West Texas Intermediate crude oil gained 5.4% in September and 30.1% during the quarter, ending at approximately $90.40 per barrel and bringing its year-to-date gain to 57.5%. Gold declined 6.3% during the month but gained 3.7% during the quarter and remains down 3.7% for the year. Copper declined 1.0% in September but is up 12.0% year-to-date. The U.S. Dollar Index gained 2.0% in September, 0.3% during the quarter, and 3.2% year-to-date. Bitcoin advanced 6.0% during the month and 42.6% during the quarter but remains down 4.6% for the year.
The third quarter demonstrated both the benefits and limitations of diversification in a rising-rate environment. Large-cap equities remained resilient, but higher Treasury yields created significant headwinds for bonds, smaller companies, and rate-sensitive sectors. Investors should remain focused on appropriate policy allocations, liquidity, diversification, and rebalancing rather than relying on perfect forecasts of inflation, interest rates, or market leadership.
Chart of the Month – The U.S. Treasury Yield Curve Resets Higher
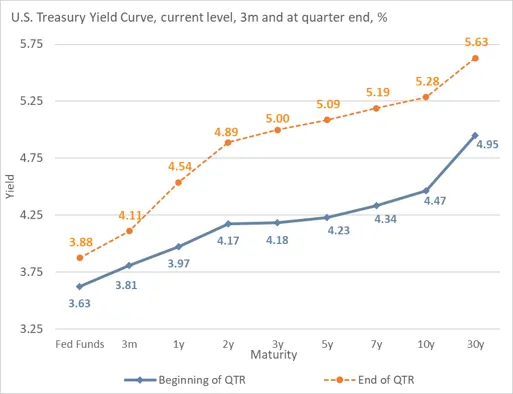
Interest rates rose sharply across the U.S. Treasury market during the quarter. The Federal Reserve increased its policy rate by 0.25%, but longer-term yields rose considerably more. The 2-year Treasury yield increased from 4.17% to 4.89%, while the 10-year yield climbed from 4.47% to 5.28%. The 30-year yield ended the quarter at 5.63%, up from 4.95%.
The chart shows that the increase was not limited to short-term rates controlled most directly by the Federal Reserve. This suggests that investors are demanding greater compensation for inflation uncertainty, large federal deficits, heavy Treasury issuance, and the risk that interest rates remain elevated for longer.
Higher yields create an immediate challenge for bond investors because bond prices fall when interest rates rise. That made the quarter particularly difficult for longer-maturity bonds, which are more sensitive to changes in rates. Higher Treasury yields can also filter through the economy by raising mortgage rates, corporate borrowing costs, and the discount rates used to value stocks and other long-duration assets.
There is also a positive side for long-term investors. New bonds can now be purchased at substantially higher yields, improving their potential income and future return. A 10-year Treasury yielding more than 5% offers a very different starting point than it did when rates were close to zero. The key is to balance that improved income opportunity against the additional price volatility that comes with longer maturities.
The message is not to abandon bonds. It is to recognize that the interest-rate environment has changed. Investors should maintain appropriate diversification, manage maturity risk carefully, and avoid building portfolios around the assumption that rates will quickly return to the unusually low levels of the prior decade.
Quote of the Month
“Interest rates are to asset prices what gravity is to the apple.” – Warren Buffett.
Major Asset Class Dashboard
Curated by Julien Frazzo, Deputy Chief Investment Officer, and Michael G. Dow, CAIA, CFA, Chief Investment Officer.
Related Links
Beacon ‘Pointe of View’ – A Market Update September 2026
Important Disclosure: The information contained in this article is for general informational purposes only. Opinions referenced are as of the publication date and may be modified due to changes in the market or economic conditions and may not necessarily come to pass. Forward-looking statements cannot be guaranteed. Past performance is not a guarantee of future results. Beacon Pointe has exercised all reasonable professional care in preparing this information. The information has been obtained from sources we believe to be reliable; however, Beacon Pointe has not independently verified or attested to the accuracy or authenticity of the information. The discussions, outlook, and viewpoints featured are not intended to be investment advice and do not consider specific investment objectives or risk tolerance you may have. All investments involve risks, including the loss of principal. Consult your financial professional for guidance specific to your circumstances. This document has been prepared with the assistance of ChatGPT Enterprise, an AI-powered tool designed to enhance productivity and provide support in drafting, editing, and organizing content. ChatGPT Enterprise leverages advanced AI models to generate text based on user input. Although ChatGPT Enterprise generates original content based on user input, there is a risk that the generated text may inadvertently resemble existing works that may not be properly cited. AI‑assisted content is reviewed by Beacon Pointe personnel for accuracy, completeness, and compliance.